What wholesale gas and network charges mean for SBU / MBU commodity costs over the next 6–12 months
The short version. Irish wholesale gas has more than doubled in a year, to about 7.6 c/kWh in September 2026. New commercial contracts are about 35% higher than last September. A further winter lift into January is the base case. SBU pays a higher bundled unit rate; MBU pays a leaner unit rate plus a capacity charge on SPC.
| 7.6 c Irish wholesale gas Sep 2026 month-to-date | +144% Wholesale vs September 2025 | ~35% New contract premium vs this time last year |
| €74 TTF benchmark €/MWh, late Sep 2026 | 1.29 c Carbon tax 2026 legislated, per kWh | 73 MWh SBU / MBU threshold (annual quantity) |
Figures are drawn from published Irish wholesale monthly averages (updated 23 September 2026), the TTF and NBP benchmarks, the legislated carbon-tax schedule, Gas Networks Ireland / CRU tariff publications, and current mid-market SBU / MBU contract ranges. This note is indicative planning material, not a live quote.
1. How SBU and MBU gas is priced
Irish commercial gas is not a single published tariff. The site is assigned a class from estimated annual consumption and Supply Point Capacity. The two classes that cover most SMEs are SBU and MBU.
| Class | Annual use | Typical sites | What is on the bill |
| SBU — Small Business User | Under 73,000 kWh | Cafés, small retail, pubs, local offices | Commodity + standing + carbon tax + VAT. Network cost mostly inside the unit rate. |
| MBU — Medium Business User | 73,000–750,000 kWh, SPC under 3,750 kWh | Hotels, schools, restaurants, light industry | Lower unit rate + standing + capacity charge on SPC + carbon tax + VAT. |
| Larger than MBU | Above 750,000 kWh | Factories, large campuses | Fuel-variation or daily-metered. Individually quoted. Outside this briefing. |
Current mid-market published ranges (ex VAT, late September 2026)
| SBU | MBU | |
| Commodity unit rate | 7.5–11.5 c/kWh | 6.2–8.5 c/kWh |
| Standing charge | €0.29–€0.63 / day | €0.41–€1.18 / day |
| Capacity / site charge | Bundled in the unit (~3.3 c) | €2.23–€3.29 (SPC-linked) |
| Carbon tax 2026 | 1.29 c/kWh | 1.29 c/kWh |
| Typical monthly spend band | Under ~€600 | ~€600–€3,000 |
New contracts written against today’s wholesale are landing toward the top of those bands, or a little above them, because September wholesale is already 7.6 c before retail margin.
2. Where wholesale sits now
Ireland’s gas price is set off the British and European hubs. Almost all Irish gas now arrives via the UK interconnectors; Corrib supplied about 17% of gas used in Ireland in the latest full year. When TTF and NBP jump, Irish commercial contracts follow within weeks on a tracker and at the next renewal on a fix.
| Month | Irish wholesale c/kWh | Change |
| September 2025 | 3.13 | — |
| December 2025 | 2.92 | Soft winter close |
| March 2026 | 5.42 | First Gulf shock |
| June 2026 | 4.37 | Seasonal dip |
| August 2026 | 6.10 | Storage / LNG tightness |
| September 2026 (to date) | 7.64 | +144% vs Sep 2025 |
| 12-month average | 4.52 | Well below the spot |
TTF is near €74/MWh. European storage in late September was reported around two-thirds full — below the usual fill for this date. LNG deliveries into Europe are restricted into early November. Forwards for new business gas are about 35% higher than September 2025.
Winter cases. A gradual improvement in Gulf LNG points to TTF around €70/MWh in the fourth quarter. A cold winter plus a further supply shock can push peak winter prices through €100/MWh. A diplomatic reopening of flows could bring peak winter back toward €50/MWh. Weather alone can swing the winter average by roughly +75% or −30%.
3. Indicative path, October 2026 to September 2027
Commodity only, c/kWh excluding VAT. SBU tracker bundles most network cost. MBU tracker is a leaner unit; capacity is extra.
| Series | Oct 26 | Jan 27 | Jun 27 | 12-m avg |
| Wholesale (central) | 7.8 | 8.8 | 5.2 | 6.8 |
| SBU tracker commodity | 11.1 | 12.1 | 8.5 | 10.1 |
| MBU tracker commodity | 9.3 | 10.3 | 6.7 | 8.3 |
| SBU 1-year fixed booked now | 10.2 | 10.2 | 10.2 | 10.2 |
| MBU 1-year fixed booked now | 7.6 | 7.6 | 7.6 | 7.6 |
| Carbon tax (legislated) | 1.29 | 1.29 | 1.44 | 1.37 |
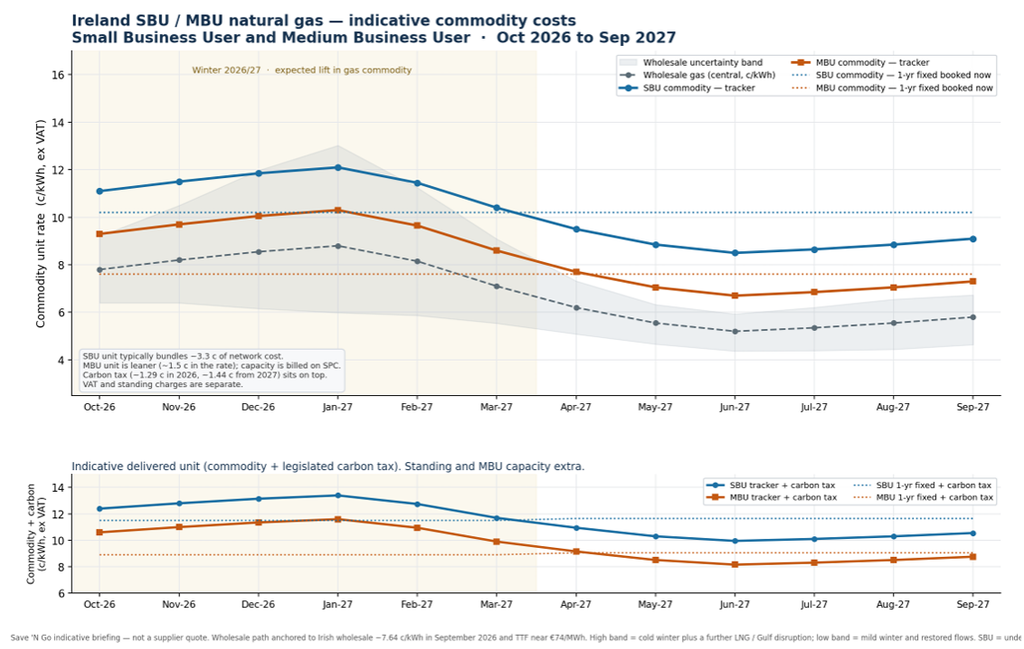
Grey band = wholesale uncertainty. High case is a cold winter plus a further LNG shock. Low case is a mild winter and restored Gulf flows. Carbon tax steps up on the legislated schedule and does not fall if wholesale falls.
4. What sits on top of the commodity line
- Carbon tax is certain. About 1.29 c/kWh in 2026 and 1.44 c in 2027, heading toward about 2.0 c by 2030 on the legislated path to €100/t.
- Network tariffs reset on 1 October each gas year. Distribution is tiered by annual quantity. Transmission is mostly a capacity charge. The 2026/27 reset is a small additional regulated lift on a typical SBU bill.
- Standing charges do not move with wholesale. They matter most on a low-use SBU.
- SPC on an MBU meter is often the quiet overpay. Capacity is reserved whether the site burns it or not. Right-sizing before a renewal is frequently worth more than a 0.2 c unit-rate win.
- VAT is applied to the bill in the usual way and is not inside the c/kWh figures in this note.
5. What this means if you come off contract this winter
A tracker will print the winter spike and the summer ease. A 12-month fix booked now locks a winter-weighted price near 10.2 c (SBU) or 7.6 c (MBU). That looks cheaper than a tracker through January and more expensive than a tracker if the central case plays out next summer. Two-year locks at this forward curve are hard to justify unless the site needs budget certainty above all else.
Practical order of work. Confirm SBU vs MBU, annual kWh and SPC. 2) Do not break a fixed contract that runs past March 2027. 3) If you renew this winter, budget SBU commodity in the 10–12 c area and MBU in the 7.5–10.5 c area, plus carbon and standing / capacity. 4) Check SPC before you sign. 5) Prefer a short fix or a tracker over a long lock at today’s winter-weighted curve.
Sources and disclaimer
Irish wholesale monthly averages current at 23 September 2026. TTF and NBP spot levels 24 September 2026. CRU / Gas Networks Ireland transmission and distribution tariff decisions for gas years 2025/26 and 2026/27. Legislated carbon-tax schedule. Mid-market SBU / MBU contract ranges current at late September 2026. Winter scenario ranges informed by published commodity-desk winter cases for TTF. No supplier is named in this briefing.
Save ’N Go · Nationwide service, Ireland & NI · info@savengo.ie · savengo.ie. Indicative market view as at 24 September 2026. Not a tender, a guarantee of future prices, or regulated financial advice. Commercial gas is individually quoted against GPRN, tariff class, SPC and 12-month consumption.
