Indicative commodity path for Fuel Variation Tariff and daily-metered / day-ahead gas over the next 6–12 months
The short version. FVT and day-ahead books sit much closer to wholesale than SBU or MBU. September wholesale is already about 7.6 c/kWh. FVT commodity on a tracker is modelled near wholesale + 0.6 c; the untraded day-ahead residual near wholesale + 0.3 c. Site charge, shrinkage, carbon tax and transmission sit on top. A 12-month strip booked now is a winter-weighted number.
| > 750 MWh FVT typical annual quantity threshold | > 3,750 kWh FVT typical SPC threshold | 7.6 c Wholesale gas Sep 2026 to date |
| +0.6 c FVT tracker adder over wholesale | +0.3 c Day-ahead residual adder over wholesale | 1.29 c Carbon tax 2026 (1.44 c from 2027) |
1. How these two books differ
| FVT — Fuel Variation Tariff | Day-ahead / daily metered | |
| Who | Typically above 750,000 kWh a year and SPC above 3,750 kWh. Factories, large buildings, process heat. | Typically monthly spend above ~€6,500. LDM / DM meters. Sites that can trade forward. |
| Commodity | Tracks wholesale plus a published fixed-cost adder (transport, swing, approved margin). Historic card range 4.5–6.0 c is stale versus today’s 7.6 c wholesale. | You buy month / quarter / season strips. Anything untraded settles at the day-ahead price plus a thin residual adder. |
| Other lines | Site charge on SPC (~€2.23–€3.16 mid-card). Fixed cost ~0.6–0.9 c. Shrinkage. Carbon tax. | Transmission and distribution capacity on MDQ / SPC. Shrinkage. Carbon tax. No bundled standing in the unit. |
| Risk | Monthly unit prints the wholesale move. Budget moves with TTF / NBP. | You choose how much to fix. Unhedged residual is the winter risk. |
Published FVT unit cards of 4.5–6.0 c/kWh were struck when wholesale sat near 4–5 c. They are not a live quote at 7.6 c wholesale. New FVT commodity will print above that card until wholesale eases.
2. Indicative commodity path (c/kWh, ex VAT)
| Series | Oct 26 | Jan 27 | Jun 27 | 12-m avg |
| Wholesale (central) | 7.8 | 8.8 | 5.2 | 6.9 |
| FVT tracker commodity | 8.4 | 9.4 | 5.8 | 7.5 |
| Day-ahead residual tracker | 8.1 | 9.1 | 5.5 | 7.2 |
| FVT 12-month strip booked now | 8.4 | 8.4 | 8.4 | 8.4 |
| Day-ahead 12-month strip booked now | 8.1 | 8.1 | 8.1 | 8.1 |
| Carbon tax | 1.29 | 1.29 | 1.44 | 1.37 |
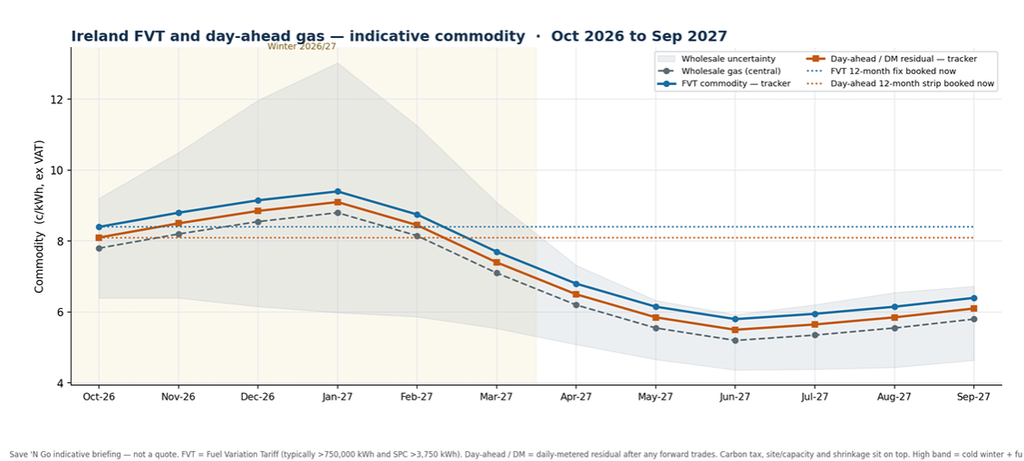
High band = cold winter plus a further LNG / Gulf shock. Low band = mild winter and restored flows. Carbon, site/capacity and shrinkage are extra.
3. What sits on top of commodity
- Carbon tax — 1.29 c/kWh until mid-October 2026, then the legislated step toward 1.44 c in 2027 (NGCT moves to €71/t from 14 October 2026).
- FVT site charge — SPC-linked, typically a few euro per day on published mid-cards. An oversized SPC is a standing tax.
- FVT fixed-cost adder — transmission and distribution commodity, UK transport, swing and margin. Historic 0.6–0.9 c.
- Shrinkage — common to all FVT / DM sites, varies monthly.
- Day-ahead capacity — transmission exit + distribution capacity on MDQ. GNI year runs 1 October. Review SPC on the May–April peak-day read.
- VAT — applied to the bill; not inside the c/kWh figures.
4. Renewal tactic for these books
Do not treat FVT like an SBU unit-rate hunt. The winning move is a hedge plan: how much of winter 2026/27 is already bought, and at what price, versus the residual that will print day-ahead in January. A 100% 24-month strip at 8.4 c looks cheap versus January 8.8 c wholesale and expensive versus a June 5.2 c central case.
Practical order of work. 1) Confirm FVT vs DM, AQ, SPC and any minimum-capacity floor from a connection agreement. 2) List open forward trades and the unhedged residual by month. 3) Do not break a strip that already covers Q4–Q1. 4) Prefer covering winter in tranches (Oct, Nov, Dec–Feb) over one 36-month lock. 5) Right-size SPC at the next review window.
Contract support
Need this handled? Save ’N Go is a leading broker for contract renewals with all leading providers. If you have a query on these figures, want a matched quote, or need support at renewal, contact us and we will facilitate it. Quotes are matched to GPRN, AQ, SPC and the open hedge book. info@savengo.ie · (01) 919 8840 · savengo.ie
Wholesale monthly averages current at 23 September 2026. TTF near €74/MWh. GNI distribution and transmission tariffs 2025/26. Legislated NGCT schedule. Mid-market FVT structure (commodity, fixed-cost adder, site charge). No supplier is named.
Save ’N Go · Nationwide · Ireland & NI · info@savengo.ie · (01) 919 8840 · savengo.ie. Indicative view as at 24 September 2026. Not a tender or a guarantee of future prices.
